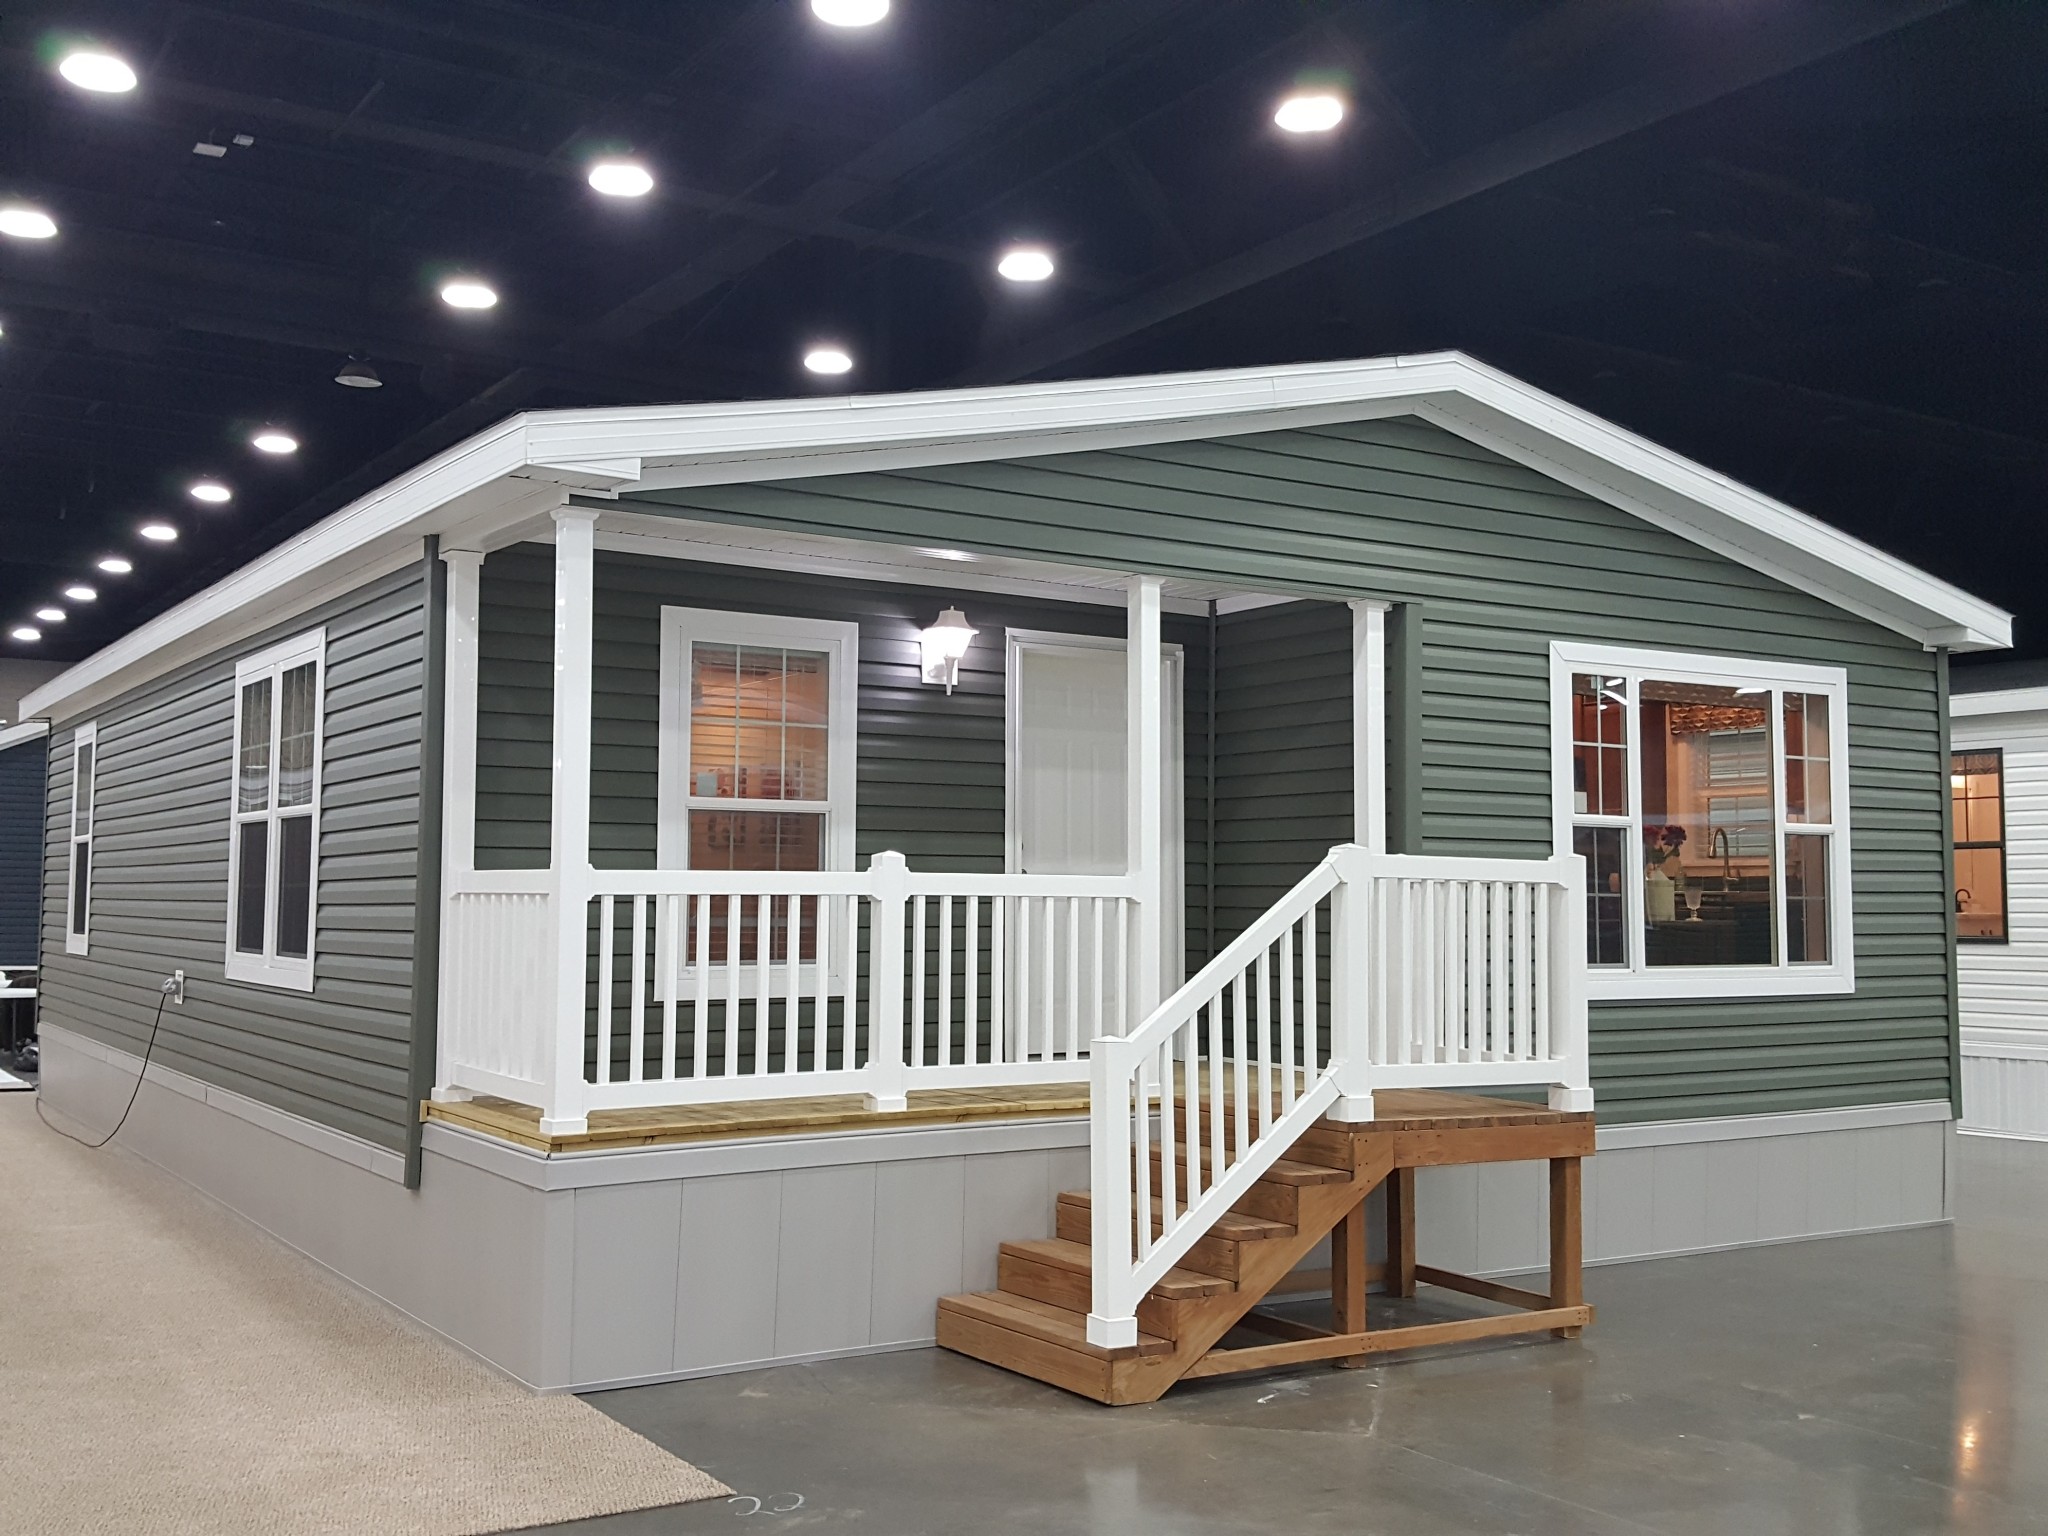
Interest rates have been on everyone's mind this year, and for mobile home buyers, they can make or break your monthly budget. The good news is that manufactured housing remains one of the most affordable paths to homeownership, even when traditional homes feel out of reach. Understanding how rates work in 2025 will help you make smarter financial decisions.
Key Takeaways
-
Mobile home loan rates in 2025 typically range from 6.75% to 12%, depending on loan type and borrower profile.
-
Chattel loans are the most common financing option and often come with higher rates than traditional mortgages.
-
Your credit score, down payment, and land ownership status all directly impact the rate you'll receive.
-
Government-backed loans like FHA and VA can offer lower rates and more flexible qualification requirements.
-
Shopping around and comparing multiple lenders is one of the best ways to secure a better deal.
Understanding Mobile Home Interest Rates in 2025
The interest rate you pay reflects how risky the loan appears to the lender. As of late 2025, manufactured home loan rates start around 6.75% for well-qualified borrowers. On the higher end, rates can climb to 10% or more for buyers with lower credit scores or those financing through chattel loans.
What catches many first-time buyers off guard is how different mobile home financing can be from traditional mortgages. Mobile homes, especially those on leased land, are often classified as personal property rather than real estate. This classification changes how lenders approach the loan.
If your home sits on land you own and is permanently attached to a foundation, you may qualify for a traditional mortgage with lower rates. However, most mobile home buyers use chattel loans, which treat the home more like a vehicle. These loans typically carry rates between 7% and 12% but process faster and have more flexible requirements.
Related: How Does Credit Scoring Work
What Factors Determine Your Rate?
Several factors influence the rate you'll receive.
Credit score is the biggest factor. Borrowers with scores above 700 generally see the best offers, while those in the 580 to 669 range will pay more.
Down payment size matters more than most people realize. Putting down 10% instead of 5% signals to lenders that you're financially stable, which often translates to a lower rate.
Land ownership affects your options significantly. Owning the land opens the door to traditional mortgage financing with lower rates. Leasing in a community means you'll likely need a chattel loan.
Debt-to-income ratio shows lenders your budget's breathing room. Most want to see total monthly debt payments stay below 43% of your gross income.
Recent housing affordability analysis shows that manufactured homes remain significantly more affordable than traditional housing. New mobile homes average around $124,000 compared to over $400,000 for conventional homes.
Types of Loans and How They Compare
Not all mobile home financing works the same way. Here's how your main options stack up:
-
Chattel Loans are the most common option. They treat your home as personal property with rates between 7% and 12%. They work well for homes in leased communities.
-
Traditional Mortgages are available if your home qualifies as real property. Rates usually fall in the 6% to 9% range.
-
FHA Loans offer competitive rates with flexible credit requirements and down payments as low as 3.5%.
-
VA Loans provide the best rates for eligible veterans and service members, with no down payment required.
Related: Guide to Different Types of Mobile Homes
How Current Economic Conditions Are Shaping the Market
The broader economic picture plays a significant role in what rates look like. After several years of elevated rates following the pandemic, 2025 has brought some stabilization.
Recent current mortgage rate trends show that conventional mortgage rates have been hovering in a range that makes timing tricky for buyers. Most financial advisors suggest focusing on what you can afford now rather than trying to time the market perfectly.
The consumer loan demand data reflects an interesting divide. Higher-income buyers can wait for better conditions, while working families are motivated to secure housing now. Mobile homes offer a practical solution for those who can't afford to wait.
Practical Strategies to Get a Better Rate
Getting the lowest possible rate takes preparation. Here's what actually moves the needle:
-
Improve your credit before applying. Check your report for errors and pay down credit card balances. Even modest score improvements can shift you into a better rate tier.
-
Save for a larger down payment. A bigger down payment reduces your loan amount and signals lower risk to lenders.
-
Shop around aggressively. Get quotes from multiple lenders, including banks, credit unions, and manufactured housing specialists.
-
Look at the APR, not just the rate. The annual percentage rate includes fees and gives you a truer picture of total loan costs.
Learning how to finance a mobile home through government-backed programs can open doors you didn't know existed. And if your credit history has some bumps, purchasing a mobile home with bad credit is absolutely possible, though you should expect higher rates until you've rebuilt your profile.
Why Mobile Homes Still Make Financial Sense
Even with interest rates running higher than buyers would prefer, manufactured homes remain a smart choice. When a new mobile home costs roughly a third of a traditional home, the total interest you'll pay is dramatically lower, even if the rate is a bit higher.
There are eight reasons to buy a mobile home that go beyond purchase price. Modern manufactured homes meet federal HUD standards, offer energy-efficient features, and can be customized to fit your lifestyle.
Ready to Explore Your Options?
Interest rates matter, but they shouldn't stop you from pursuing homeownership. Discover Home Nation's financing programs to see what's available and take the first step toward owning your home.
Final Thoughts
The interest rate environment in 2025 requires mobile home buyers to be informed and strategic. Rates aren't at historic lows, but they're not prohibitive either. What matters most is finding a loan that fits your budget and working with the right lender to get there.